When there’s a question of the benefit that tangible or intangible assets provide businesses, there are many factors that must be weighed to make internal accounting procedures effective. Businesses must determine how the cost of business assets can be expensed each year over the asset’s lifespan. Looking at how amortization and depreciation work, implementing both processes depend on the type of asset being expensed. There are noticeable differences for each method, including how to salvage value is considered, whether accelerated expensing is allowed, and how each type is expressed on financial statements.
Amortization
Amortization is an accounting practice of spreading the cost of an intangible asset over its useful life. Examples of intangible assets, according to the Internal Revenue Service’s “Section 197 Intangibles,” include goodwill, intellectual property such as trademarks, patents, and government or agency-granted permits or licenses. These are all assets that must be amortized over 15 years.
Based on IRS regulations, when it comes to determining how an asset is expensed over its useful life, amortization is most similar to the straight-line basis method of depreciation.
It’s important to note that the timeframe of amortization is subject to interpretation. Examples, according to the IRS, include a 36-month amortization timeline for computer software because it’s not categorized as an asset under the same IRS Section. Other examples not mandated to be amortized under a 15-year time frame include interests to land, business partnerships, financial contracts (such as interest rate swaps) or creation of media.
Depreciation
One of the main differences when it comes to depreciation is that it focuses on tangible or fixed assets and requires a certain percentage of its useful life to be allocated each year. Examples of assets that can be expensed include trucks for service calls, computers, printers, equipment for production, etc. Another important difference is that the asset’s salvage value is deducted from the asset’s starting cost. The remaining balance (original cost – salvage cost) determines annual expensing amounts, which is divided by the asset’s years of useful life.
Along with the above method of depreciation, also called “Straight-Line Method,” there are other ways depreciation can determine how much is expensed annually and over the asset’s useful life. For example, Declining Balance or Double Declining Balance methods are alternate ways businesses can depreciate their assets – some frontload the amounts to take advantage of accounting/tax rules to reduce their tax liabilities. Another way is to depreciate via Units of Production. This method pro-rates the level of an asset’s expected use within a particular accounting period, on a per-unit basis, to determine how much the company can expense during a particular accounting timeframe.
When it comes to accounting for goodwill, according to a November 2020 electronic survey of CFA charter holders by the CFA Institute, respondents found that investors who see amortization used by companies still require investors’ due diligence. Sixty-one percent of respondents said there need to be alternate ways to figure out if management is effective or not, and 63 percent said that amortization “distorts financial metrics.”
When it comes to understanding and navigating the differences between amortization and depreciation, business owners and investors need to be well-versed in performing due diligence to ensure compliance.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
By 2021, there were 20,000 warehouses in the United States and growing, according to the United States Bureau of Labor Statistics (BLS). With more warehouses expected to pop up in 2022 and beyond, one important consideration for businesses of all sizes is to keep track of their inventories. With different tracking and valuation methods, it’s important to understand how they work and what they can tell business owners.
Before inventory can be valued, it’s imperative to understand how it can be expressed mathematically:
Ending Inventory = Starting Inventory + Net Acquisitions – Cost of Goods Sold (COGS)
Now that inventory is better defined, understanding different approaches to inventory valuation is essential to keeping track. The first type of inventory valuation is referred to as FIFO or First In, First Out. This means that businesses sell their earliest produced inventory first and new inventory last.
Assume a company produces 500 widgets on day 1, costing $2 per widget. The same company then produces 500 widgets on day 2, costing $2.50 per widget. This method says that if 500 widgets are sold over the next week, the cost of goods sold (COGS), derived from the Income Statement, is $2 per widget because that’s how much the first 500 widgets cost to produce for inventory. The remaining widgets, 500 widgets at a cost of $2.50 per unit, would be accounted for under the ending inventory on the balance sheet.
One consideration, especially in an inflationary environment, for remaining inventory on the balance sheet is that a business might see a higher tax obligation. This is likely to occur because of higher net income due to a lower cost basis from the older inventory when assessing the COGS. Newer, more expensive inventory will naturally lead to a lower tax basis, especially if inflation falls and the retail cost is mitigated from decreased demand.
The next option is referred to as LIFO – or Last In, First Out. This means that businesses sell what they’ve produced first, then move on to the older inventory. If any inventory is left at the end of the accounting time-frame, it’s accounted for accordingly. Assuming the same 500 widgets were sold in the particular accounting period, the time-frame’s COGS would be $2.50 per widget, with the 500 widgets left over in inventory valued at the $2 per widget cost.
One important caveat to this type of valuation is with regard to inventory that’s perishable or becomes obsolete quickly (cell phones, televisions, etc.). It is not an effective method because the product will either spoil or become worth next to nothing due to highly competitive industries. For this approach, using the most recently produced goods first would lend their COGS basis to be higher. In one respect, the higher COGS basis can lower profits, but can also offset taxes due to the same effect. The third type of inventory valuation is referred to as Average Cost. This method is a way to blend LIFO and FIFO, which takes the average of inventory across all production and storage timelines. This approach averages costs in proportion to the amount of widgets produced in each run, then calculates the mean cost to determine the ending inventory and COGS figures.
[(500 x $2) + (500 x $2.50)]/1,000 = ($1,000 + $1,250)/1,000 = $2,250/1,000 = $2.25
Therefore, the average cost for inventory using this method would be $2.25 per widget.
With different types of inventory valuation explained, there are considerations that businesses should be mindful for each approach. This can make a difference to those running the company and for potential investors and lenders contemplating investing in or loaning the company money.
Inventory Valuation: How Companies Can Calculate It
December 1, 2022 · Accounting News, Blog
⏱ 3 min read
By 2021, there were 20,000 warehouses in the United States and growing, according to the United States Bureau of Labor Statistics (BLS). With more warehouses expected to pop up in 2022 and beyond, one important consideration for businesses of all sizes is to keep track of their inventories. With different tracking and valuation methods, it’s important to understand how they work and what they can tell business owners.
Before inventory can be valued, it’s imperative to understand how it can be expressed mathematically:
Ending Inventory = Starting Inventory + Net Acquisitions – Cost of Goods Sold (COGS)
Now that inventory is better defined, understanding different approaches to inventory valuation is essential to keeping track. The first type of inventory valuation is referred to as FIFO or First In, First Out. This means that businesses sell their earliest produced inventory first and new inventory last.
Assume a company produces 500 widgets on day 1, costing $2 per widget. The same company then produces 500 widgets on day 2, costing $2.50 per widget. This method says that if 500 widgets are sold over the next week, the cost of goods sold (COGS), derived from the Income Statement, is $2 per widget because that’s how much the first 500 widgets cost to produce for inventory. The remaining widgets, 500 widgets at a cost of $2.50 per unit, would be accounted for under the ending inventory on the balance sheet.
One consideration, especially in an inflationary environment, for remaining inventory on the balance sheet is that a business might see a higher tax obligation. This is likely to occur because of higher net income due to a lower cost basis from the older inventory when assessing the COGS. Newer, more expensive inventory will naturally lead to a lower tax basis, especially if inflation falls and the retail cost is mitigated from decreased demand.
The next option is referred to as LIFO – or Last In, First Out. This means that businesses sell what they’ve produced first, then move on to the older inventory. If any inventory is left at the end of the accounting time-frame, it’s accounted for accordingly. Assuming the same 500 widgets were sold in the particular accounting period, the time-frame’s COGS would be $2.50 per widget, with the 500 widgets left over in inventory valued at the $2 per widget cost.
One important caveat to this type of valuation is with regard to inventory that’s perishable or becomes obsolete quickly (cell phones, televisions, etc.). It is not an effective method because the product will either spoil or become worth next to nothing due to highly competitive industries. For this approach, using the most recently produced goods first would lend their COGS basis to be higher. In one respect, the higher COGS basis can lower profits, but can also offset taxes due to the same effect. The third type of inventory valuation is referred to as Average Cost. This method is a way to blend LIFO and FIFO, which takes the average of inventory across all production and storage timelines. This approach averages costs in proportion to the amount of widgets produced in each run, then calculates the mean cost to determine the ending inventory and COGS figures.
[(500 x $2) + (500 x $2.50)]/1,000 = ($1,000 + $1,250)/1,000 = $2,250/1,000 = $2.25
Therefore, the average cost for inventory using this method would be $2.25 per widget.
With different types of inventory valuation explained, there are considerations that businesses should be mindful for each approach. This can make a difference to those running the company and for potential investors and lenders contemplating investing in or loaning the company money.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Now is the time of year to do everything you can to minimize taxes and maximize your financial health with proper year-end planning. In this article, we’ll look at several actions to consider taking before the end of 2022.
Thoughtfully Harvest Losses and Gains Before Year-End
Tax loss harvesting by selling securities at a loss to offset capital gains is a classic year-end planning strategy. Just make sure not to violate the wash sale rules. This means you can’t buy back the same security or a substantially identical one within 30 days of the sale.
Reinvest Capital Gains into Opportunity Zones
Another way to offset capital gains is to reinvest those gains into a qualified opportunity fund (QOF). To be eligible, you must make the investment within 180 days of the sale of the asset-bearing gains. QOF investments allow you to defer the recognition of the capital gains tax on the original investment. The details and exact rules can be tricky, so it’s best to check with your tax advisor before making this type of transaction.
Consider Installment Sales Where Applicable
When a taxpayer sells a private asset such as real estate, a business, or private equity in exchange for a series of payments over multiple years through a promissory note, this can constitute an installment sale. Installment sales are generally taxed, with each payment representing a portion of the proceeds; return of basis, interest, and gain are recognized over the life of the note.
There are situations in which installment sales can be structured so that gains are not recognized until principal payments are recouped. If you are considering selling an asset via an installment sale this year-end or next, consult with your tax advisor to determine if it’s possible to structure the sale to defer gains.
Funding Retirement
If you can contribute to a retirement account, now is the time to see if you need to make additional contributions or top-up to the full amount allowable. As you review your situation, keep in mind the annual maximum contribution limits for 2022.
IRAs – $6,000. If you are 50 or older, it’s $7,000.
401(k)s/403(b)s — $20,500. If you are 50 or older, it’s $27,000
Also, converting assets from a traditional IRA to a Roth IRA may be a smart move if: you believe your tax rate will be higher in the future; you can afford to pay the taxes now with spare cash; and you don’t plan to leave the IRA assets to charity.
Take Your Required Minimum Distributions
The annual deadline to take required minimum distributions (RMD) from your own or inherited retirement accounts is Dec. 31, 2022. It’s important to take RMDs because there is a 50 percent penalty on amounts not distributed. The amount needed to be taken were determined on Dec. 31, 2021, even though the value of the investment has likely fluctuated significantly since that time. RMDs are based on a calculation of age and amount of assets. There are online calculators to help you figure out the amount you need to take.
Giving to Charity
Some taxpayers believe that the deduction for charitable donations is no longer applicable to them since it can be hard to make donations large enough to exceed the standard deduction. One strategy to overcome this challenge is to cluster your donations. Instead of making equal gifts every year, consider making more substantial gifts all in one year instead.
When it comes to making donations around year-end, it’s important to understand the rules on timing and when a gift is effectively deemed given for tax purposes. Here are the basic rules on timing of charitable donations.
To give to charity by check => the date the check is mailed
Gifts of stock certificates => when the transfer occurs, according to the issuer’s records
Gifts of stocks by electronic transfer => when the stock is received, according to the issuer’s records
Gifts by credit card => date the charge is made
Conclusion
As we enter the final part of the year, now is the time to take stock of your financial and tax situation to see if there are any moves you can make to minimize your 2022 tax liabilities and maximize your wealth.
The 2022 Tax Guide
December 1, 2022 · Blog, Tax and Financial News
⏱ 4 min read
Now is the time of year to do everything you can to minimize taxes and maximize your financial health with proper year-end planning. In this article, we’ll look at several actions to consider taking before the end of 2022.
Thoughtfully Harvest Losses and Gains Before Year-End
Tax loss harvesting by selling securities at a loss to offset capital gains is a classic year-end planning strategy. Just make sure not to violate the wash sale rules. This means you can’t buy back the same security or a substantially identical one within 30 days of the sale.
Reinvest Capital Gains into Opportunity Zones
Another way to offset capital gains is to reinvest those gains into a qualified opportunity fund (QOF). To be eligible, you must make the investment within 180 days of the sale of the asset-bearing gains. QOF investments allow you to defer the recognition of the capital gains tax on the original investment. The details and exact rules can be tricky, so it’s best to check with your tax advisor before making this type of transaction.
Consider Installment Sales Where Applicable
When a taxpayer sells a private asset such as real estate, a business, or private equity in exchange for a series of payments over multiple years through a promissory note, this can constitute an installment sale. Installment sales are generally taxed, with each payment representing a portion of the proceeds; return of basis, interest, and gain are recognized over the life of the note.
There are situations in which installment sales can be structured so that gains are not recognized until principal payments are recouped. If you are considering selling an asset via an installment sale this year-end or next, consult with your tax advisor to determine if it’s possible to structure the sale to defer gains.
Funding Retirement
If you can contribute to a retirement account, now is the time to see if you need to make additional contributions or top-up to the full amount allowable. As you review your situation, keep in mind the annual maximum contribution limits for 2022.
IRAs – $6,000. If you are 50 or older, it’s $7,000.
401(k)s/403(b)s — $20,500. If you are 50 or older, it’s $27,000
Also, converting assets from a traditional IRA to a Roth IRA may be a smart move if: you believe your tax rate will be higher in the future; you can afford to pay the taxes now with spare cash; and you don’t plan to leave the IRA assets to charity.
Take Your Required Minimum Distributions
The annual deadline to take required minimum distributions (RMD) from your own or inherited retirement accounts is Dec. 31, 2022. It’s important to take RMDs because there is a 50 percent penalty on amounts not distributed. The amount needed to be taken were determined on Dec. 31, 2021, even though the value of the investment has likely fluctuated significantly since that time. RMDs are based on a calculation of age and amount of assets. There are online calculators to help you figure out the amount you need to take.
Giving to Charity
Some taxpayers believe that the deduction for charitable donations is no longer applicable to them since it can be hard to make donations large enough to exceed the standard deduction. One strategy to overcome this challenge is to cluster your donations. Instead of making equal gifts every year, consider making more substantial gifts all in one year instead.
When it comes to making donations around year-end, it’s important to understand the rules on timing and when a gift is effectively deemed given for tax purposes. Here are the basic rules on timing of charitable donations.
To give to charity by check => the date the check is mailed
Gifts of stock certificates => when the transfer occurs, according to the issuer’s records
Gifts of stocks by electronic transfer => when the stock is received, according to the issuer’s records
Gifts by credit card => date the charge is made
Conclusion
As we enter the final part of the year, now is the time to take stock of your financial and tax situation to see if there are any moves you can make to minimize your 2022 tax liabilities and maximize your wealth.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Data has become a primary asset for businesses today. Consequently, the survival of a business in our data-driven environment is highly dependent on the ability to have total control over data storage, extraction, and manipulation.
As businesses continue being bombarded with vast volumes of data, datafication has become a big trend that provides a solution to turn data into quantifiable, usable, and actionable information.
What is Datafication?
The term datafication was coined by Kenneth Cukier and Victor Mayer-Schöenberger in 2013 when they explained it as the transformation of social actions into quantifiable data.
Today, much data is collected at the point of contact with any technology device. Aside from data such as text, images, and numbers, there are logins, passwords, device activity logs, clicks, interaction times, and more. Datafication helps translate all of these human activities into data, which is then repackaged in a form that offers value.
In business, datafication means converting every activity of a business model into actionable data. This has been enabled by a rise in technologies such as artificial intelligence, machine learning, big data analytics, and predictive analytics.
It’s worth noting that datafication is not the same as digitization. While datafication is about taking all aspects of life and turning them into a data format, digitization involves converting analog content, such as images and text, to a digital format.
Examples of Datafication in Real Life
There are various ways datafication has been applied in real life, including:
Social media platforms – a lot of data is found on social platforms through profile updates, preferences, reactions, comments and posts. Such information is used for customer profiling.
Ad personalization – tech giants such as Facebook, Google, Apple and Amazon are already using collected data in their storage to personalize their ads and target potential customers.
In customer relationship management – data collected through language and tone in emails, social media and phone calls are used to understand customer needs and wants as well as buying behavior and personalities.
Human resources – HR uses data obtained from social media or mobile apps to discover characteristics and personalities when looking for potential employees. They also use the data to assess employee productivity. This means that it may no longer be necessary to take personality tests, as the collected data can be analyzed to check if a person matches the company culture and role for which he applies.
Insurance and banking – understanding the risk profile of a customer applying for insurance or a loan, as the data is used to assess the client’s trustworthiness.
Datafication for Competitive Advantage
With the above use cases, it is evident that businesses can leverage datafication to help improve operations, thereby increasing productivity and revenue.
For instance, collecting real-time customer feedback can help improve products and services. Additionally, it becomes easy to determine and predict sales by analyzing data from social platforms such as Facebook, Instagram and Twitter.
The information collected from social media, emails and other digital platforms is then used to create personalized campaigns, effectively targeting the most interested audience.
How Businesses Can Implement Datafication
Any trending technology that presents benefits to a business comes at a cost. Luckily, cloud computing eases datafication for businesses as they don’t have to worry about acquiring necessary hardware and software. With readily available software as a service (SaaS) or platform as a service (PaaS) technologies, businesses need only to define the goal they want to achieve with the data collected.
The main concern of a business remains the proper implementation of datafication. To begin with, it is best to ensure that the right technology – such as mobile devices, voice assistants, wearables, IoT – is used.
Next is to use appropriate platforms. Using the right platform will help effectively extract data that a business needs. Such platforms should also analyze massive amounts of data and produce reports that enhance decision-making.
Another critical factor is to have a centralized repository where all authorized people in the organization can access the data.
Finally, it’s crucial to have skilled professionals in data infrastructure, data management and data analytics to evaluate and manage the data. This could either be an in-house team or outsourced.
Conclusion
Businesses that wish to remain relevant must consider datafication as part of their digital strategies. However, as datafication enters digital transformation, its successful implementation will require attention to data protection through adhering to legal requirements, technical measures such as access control, and best business practices.
What is Datafication, and Should Business Leaders Take Notice?
December 1, 2022 · Blog, What's New in Technology
⏱ 4 min read
Data has become a primary asset for businesses today. Consequently, the survival of a business in our data-driven environment is highly dependent on the ability to have total control over data storage, extraction, and manipulation.
As businesses continue being bombarded with vast volumes of data, datafication has become a big trend that provides a solution to turn data into quantifiable, usable, and actionable information.
What is Datafication?
The term datafication was coined by Kenneth Cukier and Victor Mayer-Schöenberger in 2013 when they explained it as the transformation of social actions into quantifiable data.
Today, much data is collected at the point of contact with any technology device. Aside from data such as text, images, and numbers, there are logins, passwords, device activity logs, clicks, interaction times, and more. Datafication helps translate all of these human activities into data, which is then repackaged in a form that offers value.
In business, datafication means converting every activity of a business model into actionable data. This has been enabled by a rise in technologies such as artificial intelligence, machine learning, big data analytics, and predictive analytics.
It’s worth noting that datafication is not the same as digitization. While datafication is about taking all aspects of life and turning them into a data format, digitization involves converting analog content, such as images and text, to a digital format.
Examples of Datafication in Real Life
There are various ways datafication has been applied in real life, including:
Social media platforms – a lot of data is found on social platforms through profile updates, preferences, reactions, comments and posts. Such information is used for customer profiling.
Ad personalization – tech giants such as Facebook, Google, Apple and Amazon are already using collected data in their storage to personalize their ads and target potential customers.
In customer relationship management – data collected through language and tone in emails, social media and phone calls are used to understand customer needs and wants as well as buying behavior and personalities.
Human resources – HR uses data obtained from social media or mobile apps to discover characteristics and personalities when looking for potential employees. They also use the data to assess employee productivity. This means that it may no longer be necessary to take personality tests, as the collected data can be analyzed to check if a person matches the company culture and role for which he applies.
Insurance and banking – understanding the risk profile of a customer applying for insurance or a loan, as the data is used to assess the client’s trustworthiness.
Datafication for Competitive Advantage
With the above use cases, it is evident that businesses can leverage datafication to help improve operations, thereby increasing productivity and revenue.
For instance, collecting real-time customer feedback can help improve products and services. Additionally, it becomes easy to determine and predict sales by analyzing data from social platforms such as Facebook, Instagram and Twitter.
The information collected from social media, emails and other digital platforms is then used to create personalized campaigns, effectively targeting the most interested audience.
How Businesses Can Implement Datafication
Any trending technology that presents benefits to a business comes at a cost. Luckily, cloud computing eases datafication for businesses as they don’t have to worry about acquiring necessary hardware and software. With readily available software as a service (SaaS) or platform as a service (PaaS) technologies, businesses need only to define the goal they want to achieve with the data collected.
The main concern of a business remains the proper implementation of datafication. To begin with, it is best to ensure that the right technology – such as mobile devices, voice assistants, wearables, IoT – is used.
Next is to use appropriate platforms. Using the right platform will help effectively extract data that a business needs. Such platforms should also analyze massive amounts of data and produce reports that enhance decision-making.
Another critical factor is to have a centralized repository where all authorized people in the organization can access the data.
Finally, it’s crucial to have skilled professionals in data infrastructure, data management and data analytics to evaluate and manage the data. This could either be an in-house team or outsourced.
Conclusion
Businesses that wish to remain relevant must consider datafication as part of their digital strategies. However, as datafication enters digital transformation, its successful implementation will require attention to data protection through adhering to legal requirements, technical measures such as access control, and best business practices.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Believe it or not, the year is coming to a close. If you want to finish strong and set attainable goals for 2023, here’s a handy, actionable checklist to help you navigate upcoming expenditures.
Review Your Spending and Create a Budget
This might seem like Finance 101, but it’s a tried and true method that works. Take a look back to see where your money went. When you’ve evaluated your patterns of spending, you can reset priorities for the New Year, assuming you want to make changes. If you do, sit down and create a budget. Your tax professional will probably have a downloadable tax planning guild so ask them first, but here’s an example of a family-friendly free, downloadable template to get you started on your 2023 plan.
Rethink Your Savings
If you already have a healthy amount in savings, congrats. Make sure it’s an account that’s interest-bearing and you have the best rate. However, if you had to dip into your emergency savings, then chart a course to replenish it. If you don’t have an emergency fund, it makes good sense to start one. A smart rule to consider is having six months of income saved up, should your heater go out, you experience a sudden job loss, or suffer unforeseen medical expenses that your insurance doesn’t cover. A no-nonsense way to begin is to automate a certain amount each month that will be deducted from your paycheck. You’ll begin to accumulate money in no time. Best of all, you’ll never miss it.
Evaluate Your Debt
Have you made progress in paying it down? Or have you gone the other way? If you’ve eliminated your debt, once again, congrats. If you’ve increased your debt, don’t despair because there are some easy ways to cut expenses. Slow down on eating out. Review your subscriptions and see which ones you really need. Here’s a list of more areas to consider. Another way to get rid of the shackles of debt is to apply for a consolidation loan. You might also use the debt snowball method—starting with the smallest debt and working your way up to the largest. Or the inverse, the debt avalanche, where you pay off high-interest rate balances first.
Contribute to Your 401(k) by Dec. 31
You still have time to do this, but make sure it happens before the clock strikes midnight on Dec. 31. If you’re fortunate enough to receive a year-end bonus, you might want to put as much of it as you can toward your 401(k) plan. For the New Year, increase the amount you’re contributing. Just one or more percentage points higher can make a big difference. Finally, if your company offers a match that you have yet to take advantage of (read: max out), do so before it’s too late.
Consider a Roth Conversion
If you’ve experienced a loss of income this year, you may be in a lower tax bracket. This means you can take advantage of your situation by converting some of your pre-tax assets like a Traditional IRA into a Roth IRA. If you’ve earned too much to convert to a Roth IRA, a back-door Roth IRA contribution might be the way to go. Here’s how you do it: Deposit money into a non-deductible Traditional IRA, then convert that IRA into a Roth IRA. But before you do anything at all, consult your tax advisor, as there are potential costs and tax liabilities that might come up.
Check your FSA Balance
An FSA (Flexible Spending Account) is a great benefit if your employer offers it. However, check your balance to see how much you have left because the rule is: Use it or lose it. That said, many companies offer a grace period until mid-March to spend what you have left, though not all do. Make sure to inquire about the rules of your account before the New Year.
Get a Free Credit Report
When was the last time you checked your credit? If you haven’t done so, now’s a good time because looking back can help you plan ahead. Here’s a great place to get a free report. If you notice any errors or discover any identity theft, you can immediately take steps to correct them and start with a clean slate for 2023.
While taking care of financial matters at the end of the year can be a love/hate kind of thing to do, if you spend a little time now, the coming days might be substantially merrier and bright.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Some businesses, especially publicly traded ones, may choose accrual accounting to reduce volatility in earnings, while start-ups or small businesses may choose to go with a cash basis accounting option. A poll conducted by the Journal of Accountancy on Topic 606 discovered that one in five respondents reported that one of the most common audit perils for their clients was the risk of evaluating “material misstatement” when it comes to recognizing revenue under Topic 606.
According to the Association of International Certified Professional Accountants (AICPA) and the Financial Accounting Standards Board’s (FASB) Accounting Standards Topic 606, proper revenue recognition involves following five steps. While each step requires exercising judgment, the following is a brief overview.
Step 1
When all the following criteria is satisfied in the first step to establish a contract with their client, an organization should follow the revenue recognition standard mandates when an agreement falls within such criteria.
All contract parties have agreed to the terms of the contract and are engaged in fulfilling their agreed-to commitments. All party’s rights are easily identifiable when it comes to goods/services to be exchanged. Payment is clearly described for the goods/services to be delivered. The recipient’s cash flows are expected to change based upon the contract’s deliverables. The organization that provides the product or service should have “a reasonable expectation” of receiving consideration from the customer and they have a reasonable expectation the customer is able and willing to provide such payment.
Step 2
The second step is to determine what each party of the contract must fulfill to satisfy their respective contractual obligations. This is what businesses pledge to customers and clients while delivering their unique product or service. This step is where each performance obligation should be identified as unique. If each performance obligation does not qualify as unique, based upon this standard, it must be packaged with other goods or services until it meets such criteria.
The FASB AICPA ASC 606 standards explains if both of the following apply, a good or service is considered “distinct:”
If the receiving party can receive a useful product or professional assistance by itself or in conjunction with related materials the client had pre-existing to the contract in question;
AND
The business’ contractual pledge to deliver the service or finished materials is individually distinguishable from additional pledges from the contract.
Step 3
The third step is to calculate the financial terms of the deal. This entails how much money the business anticipates receiving in return for delivering the goods or services, minus portions related to that of external organizations. This can include taxes businesses must collect for local, state or federal government agencies. Other examples of this include “variable consideration” – or how much consideration a company will receive, bearing in mind financial adjustments in conjunction with delivering their product or service. Businesses should estimate the impact of such variable costs and what they might be allowed while fulfilling their contractual obligations. Examples can include financial enticements, fines, reimbursements, price cuts, etc.
Step 4
The fourth step is to figure out how much it will cost parties to fulfill their responsibilities spelled out in the legal agreement. When attempting to recognize revenue according to Topic 606, if there’s multiple distinct responsibilities, the business is required to break down the price based on “each separate performance obligation in an amount” that is commensurate to an amount the business is expected to receive for each “separate performance obligation.” This means looking at each piece of the contract as a unique “performance obligation.”
When the transaction is subject to a discount or “variable consideration,” businesses may or may not assign the price concession or “variable consideration” to one or more performance obligations versus across the agreement’s full list of “performance obligations.” If the business offers markdowns of the goods or services, in addition to adjusting the “transaction prices,” there should be proportional and estimated calculations when it comes to recognizing revenue.
Step 5
The fifth step says that once a business has satisfied its “performance obligation” set out in the contract, revenue can be recognized. This occurs when the customer receives their contracted goods or services, which is when they have complete command of the property. This can be illustrated when the customer can increase their cash flow, use it as an asset to obtain financing, leverage pre-existing equipment or service delivery, etc.
When it comes to recognizing revenue under Topic 606, this is just the beginning of how businesses can analyze and interpret the many nuances of this accounting topic.
Dissecting the Revenue Recognition Principle
November 1, 2022 · Accounting News, Blog
⏱ 4 min read
Some businesses, especially publicly traded ones, may choose accrual accounting to reduce volatility in earnings, while start-ups or small businesses may choose to go with a cash basis accounting option. A poll conducted by the Journal of Accountancy on Topic 606 discovered that one in five respondents reported that one of the most common audit perils for their clients was the risk of evaluating “material misstatement” when it comes to recognizing revenue under Topic 606.
According to the Association of International Certified Professional Accountants (AICPA) and the Financial Accounting Standards Board’s (FASB) Accounting Standards Topic 606, proper revenue recognition involves following five steps. While each step requires exercising judgment, the following is a brief overview.
Step 1
When all the following criteria is satisfied in the first step to establish a contract with their client, an organization should follow the revenue recognition standard mandates when an agreement falls within such criteria.
All contract parties have agreed to the terms of the contract and are engaged in fulfilling their agreed-to commitments. All party’s rights are easily identifiable when it comes to goods/services to be exchanged. Payment is clearly described for the goods/services to be delivered. The recipient’s cash flows are expected to change based upon the contract’s deliverables. The organization that provides the product or service should have “a reasonable expectation” of receiving consideration from the customer and they have a reasonable expectation the customer is able and willing to provide such payment.
Step 2
The second step is to determine what each party of the contract must fulfill to satisfy their respective contractual obligations. This is what businesses pledge to customers and clients while delivering their unique product or service. This step is where each performance obligation should be identified as unique. If each performance obligation does not qualify as unique, based upon this standard, it must be packaged with other goods or services until it meets such criteria.
The FASB AICPA ASC 606 standards explains if both of the following apply, a good or service is considered “distinct:”
If the receiving party can receive a useful product or professional assistance by itself or in conjunction with related materials the client had pre-existing to the contract in question;
AND
The business’ contractual pledge to deliver the service or finished materials is individually distinguishable from additional pledges from the contract.
Step 3
The third step is to calculate the financial terms of the deal. This entails how much money the business anticipates receiving in return for delivering the goods or services, minus portions related to that of external organizations. This can include taxes businesses must collect for local, state or federal government agencies. Other examples of this include “variable consideration” – or how much consideration a company will receive, bearing in mind financial adjustments in conjunction with delivering their product or service. Businesses should estimate the impact of such variable costs and what they might be allowed while fulfilling their contractual obligations. Examples can include financial enticements, fines, reimbursements, price cuts, etc.
Step 4
The fourth step is to figure out how much it will cost parties to fulfill their responsibilities spelled out in the legal agreement. When attempting to recognize revenue according to Topic 606, if there’s multiple distinct responsibilities, the business is required to break down the price based on “each separate performance obligation in an amount” that is commensurate to an amount the business is expected to receive for each “separate performance obligation.” This means looking at each piece of the contract as a unique “performance obligation.”
When the transaction is subject to a discount or “variable consideration,” businesses may or may not assign the price concession or “variable consideration” to one or more performance obligations versus across the agreement’s full list of “performance obligations.” If the business offers markdowns of the goods or services, in addition to adjusting the “transaction prices,” there should be proportional and estimated calculations when it comes to recognizing revenue.
Step 5
The fifth step says that once a business has satisfied its “performance obligation” set out in the contract, revenue can be recognized. This occurs when the customer receives their contracted goods or services, which is when they have complete command of the property. This can be illustrated when the customer can increase their cash flow, use it as an asset to obtain financing, leverage pre-existing equipment or service delivery, etc.
When it comes to recognizing revenue under Topic 606, this is just the beginning of how businesses can analyze and interpret the many nuances of this accounting topic.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Planning for Animal Wellness Act /PAW Act (S 4205) – Introduced by Sen. Gary Peters (D-MI) on May 12, this act instructs the Federal Emergency Management Agency (FEMA) to compile best practices and federal guidance for handling household pets, service and assistance animals and captive animals during emergencies and disasters. Initiatives include preparedness (e.g., sheltering and evacuation planning), response and recovery.The bill passed in the Senate on Aug. 6, in the House on Sept. 14 and was signed into law on Oct. 17 by President Biden.
Bulb Replacement Improving Government with High-Efficiency Technology Act/BRIGHT Act (S 442) – Presently, public buildings managed by the General Services Administration (GSA) must be equipped with energy-efficient lightbulbs and fixtures. This new bill expands requirements to ensure buildings are equipped with the most cost-effective and energy-efficient lighting systems available. Procurement must take into consideration factors such as motion sensors, fixture distribution and other elements. The act was introduced by Sen. Gary Peters (D-MI) on Feb. 25, 2021. It passed in the Senate on March 30, the House on Sept. 14 and was enacted into law on Sept. 17.
FTC Collaboration Act of 2021 (HR 1766) – Introduced by Rep. Tom O’Halleran (D-AZ) on March 10, 2021, this bill authorizes the Federal Trade Commission (FTC) to work with state attorneys general to evaluate procedures, such as accountability mechanisms, to better facilitate efforts to prevent and detect fraud and scams. FTC proposals must provide the opportunity for public comment, then submit legislative recommendations based on the results of the study. This bill passed in the House on April 14, 2021, and in the Senate on Sept. 29, 2022. It was signed into law on Oct. 10.
Expedited Delivery of Airport Infrastructure Act of 2021 (HR 468) – This legislation was introduced by Rep. Sam Graves (R-MO) on Jan. 25, 2021, to amend Title 49 of the United States Code. New provisions allow for incentive payments to expedite certain federally financed airport development projects, subject to an allowable project cost standard. The bill passed in the House on June 15, 2021, the Senate on Sept. 27, 2022, and was signed into law on Oct. 10.
Supporting Families of the Fallen Act (S2794) – This legislation impacts service members (or former members) covered by the Servicemembers’ Group Life Insurance program and the Veterans’ Group Life Insurance program. Specifically, it increases the maximum life insurance coverage amount from $400,000 to $500,000. The bill was introduced by Sen. Tommy Tuberville (R-AL) on Sept. 22, 2021. It was passed in the Senate on March 23, 2022, and in the House on Sept. 29. It was signed into law by the president on Sept. 17.
Global Malnutrition Prevention and Treatment Act of 2021 (HR 4693) – Introduced on July 26, 2021, by Rep. Michael McCaul (R-TX), this bipartisan bill directs the U.S. Agency for International Development (USAID) to develop initiatives designed to prevent and treat malnutrition globally. The USAID is charged with choosing recipient countries based on specified malnutrition-related indicators. These initiatives andcountry selections must be made within five years, and the provisions are scheduled to terminate seven years after the bill’s enactment. The bill passed in the House with a 90 percent vote on April 27, 2022, in the Senate on Sept. 20, 2022, and was signed into law on Oct. 19.
Global Food Security Reauthorization Act of 2022 (HR 8446) – This act reauthorizes funding to support the government Global Food Security Strategy and the Emergency Food Strategy programs through fiscal year 2028. The first program is designed to promote nutrition and food security, with a newly enhanced focus on improving efficiency and reliability in agriculture production. The latter program provides market-based assistance throughout the world. The bill was introduced by Rep. Betty McCollum (D-MN) on July 20. With 78 percent of the vote, it was passed in the House on Sept. 29 and is currently under consideration in the Senate.
Saving Animals, Enhancing Government Efficiency, and Supporting Global Food Security
November 1, 2022 · Blog, Congress at Work
⏱ 4 min read
Planning for Animal Wellness Act /PAW Act (S 4205) – Introduced by Sen. Gary Peters (D-MI) on May 12, this act instructs the Federal Emergency Management Agency (FEMA) to compile best practices and federal guidance for handling household pets, service and assistance animals and captive animals during emergencies and disasters. Initiatives include preparedness (e.g., sheltering and evacuation planning), response and recovery.The bill passed in the Senate on Aug. 6, in the House on Sept. 14 and was signed into law on Oct. 17 by President Biden.
Bulb Replacement Improving Government with High-Efficiency Technology Act/BRIGHT Act (S 442) – Presently, public buildings managed by the General Services Administration (GSA) must be equipped with energy-efficient lightbulbs and fixtures. This new bill expands requirements to ensure buildings are equipped with the most cost-effective and energy-efficient lighting systems available. Procurement must take into consideration factors such as motion sensors, fixture distribution and other elements. The act was introduced by Sen. Gary Peters (D-MI) on Feb. 25, 2021. It passed in the Senate on March 30, the House on Sept. 14 and was enacted into law on Sept. 17.
FTC Collaboration Act of 2021 (HR 1766) – Introduced by Rep. Tom O’Halleran (D-AZ) on March 10, 2021, this bill authorizes the Federal Trade Commission (FTC) to work with state attorneys general to evaluate procedures, such as accountability mechanisms, to better facilitate efforts to prevent and detect fraud and scams. FTC proposals must provide the opportunity for public comment, then submit legislative recommendations based on the results of the study. This bill passed in the House on April 14, 2021, and in the Senate on Sept. 29, 2022. It was signed into law on Oct. 10.
Expedited Delivery of Airport Infrastructure Act of 2021 (HR 468) – This legislation was introduced by Rep. Sam Graves (R-MO) on Jan. 25, 2021, to amend Title 49 of the United States Code. New provisions allow for incentive payments to expedite certain federally financed airport development projects, subject to an allowable project cost standard. The bill passed in the House on June 15, 2021, the Senate on Sept. 27, 2022, and was signed into law on Oct. 10.
Supporting Families of the Fallen Act (S2794) – This legislation impacts service members (or former members) covered by the Servicemembers’ Group Life Insurance program and the Veterans’ Group Life Insurance program. Specifically, it increases the maximum life insurance coverage amount from $400,000 to $500,000. The bill was introduced by Sen. Tommy Tuberville (R-AL) on Sept. 22, 2021. It was passed in the Senate on March 23, 2022, and in the House on Sept. 29. It was signed into law by the president on Sept. 17.
Global Malnutrition Prevention and Treatment Act of 2021 (HR 4693) – Introduced on July 26, 2021, by Rep. Michael McCaul (R-TX), this bipartisan bill directs the U.S. Agency for International Development (USAID) to develop initiatives designed to prevent and treat malnutrition globally. The USAID is charged with choosing recipient countries based on specified malnutrition-related indicators. These initiatives andcountry selections must be made within five years, and the provisions are scheduled to terminate seven years after the bill’s enactment. The bill passed in the House with a 90 percent vote on April 27, 2022, in the Senate on Sept. 20, 2022, and was signed into law on Oct. 19.
Global Food Security Reauthorization Act of 2022 (HR 8446) – This act reauthorizes funding to support the government Global Food Security Strategy and the Emergency Food Strategy programs through fiscal year 2028. The first program is designed to promote nutrition and food security, with a newly enhanced focus on improving efficiency and reliability in agriculture production. The latter program provides market-based assistance throughout the world. The bill was introduced by Rep. Betty McCollum (D-MN) on July 20. With 78 percent of the vote, it was passed in the House on Sept. 29 and is currently under consideration in the Senate.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Are you a trader or an investor? The difference is frequently discerned by how closely you monitor the stock market and how quickly you move in and out of investments. Traders are often referred to as market timers because they actively seek to buy into positions when share prices drop, and sell out when those prices rise.
Many financial planners and professional money managers are not strong proponents of market timing. The reality is that no one can predict market movements accurately over the long term, so success is often a matter of luck and opportunity.
However, market timing is not the same as having a carefully structured and disciplined investment exit strategy. One reason this is important is that it can help prevent investors from panic selling. If you have considered the growth potential and market risks of a particular security or type of investment, and you put parameters in place that reflect your comfort level, then you can control your losses to a great extent. Without this analysis, you may be subject to emotional responses and sell for a significant loss because you can’t take the stress of watching your investment lose money day after day.
Exit Strategy
When share prices drop unexpectedly – and continue to fall – many investors let their emotions get the best of them and sell prematurely. Having a preconceived exit strategy is a good way to prevent this type of panic selling.
An exit strategy basically means that you set a target sell price, but it’s important that you have the discipline to sell at that price. Often when a stock’s share price is rising quickly, it is tempting to “let it ride” and ignore your exit strategy. However, that tide could change quickly in the other direction, turning a profitable trade into a loss. When this happens, you may stubbornly hang on to that declining stock knowing that you missed your opportunity to cash in – and hope that it will come around again.
An effective exit strategy should have two plans in place; a price point to sell for a gain and a price point to sell for a loss. This tactic can help keep your asset allocation strategy on target by not letting gains or losses in any one position throw your target asset allocation percentages out of whack. At the same time, you can manage risk by not allowing your portfolio to lose too much money. There are certain tactics that can help implement your exit strategy. For example:
Stop-Loss – an order to sell a security when its price is declining at the point when it reaches your assigned stop price (sell-stop).
Stop-Limit – a limit order gives instructions to sell a stock at a minimum price point. Stop-limit orders can be set to expire at the end of the current market session or carried over to future trading sessions (GTC – good ‘til canceled).
Trailing Stop – a modified stop order that can be set as either a percentage or dollar amount below or above the market price of a security.
Tax Considerations
An investor’s exit strategy should take into consideration potential taxes on capital gains. The amount you pay depends on how long you hold a position. If held for less than one year, the short-term capital gains tax rate is the same as your regular income tax. If held for one year or longer, the tax rate is 0 percent, 15 percent or 20 percent – depending on income tax bracket and filing status. When determining your exit strategy, it is prudent to set a long-term perspective with a plan to harvest gains on positions more than a year old.
Risk Management
Setting up an exit strategy is one component of a risk management plan. The following are other complementary strategies you can deploy to set boundaries on how much money you are willing lose.
Risk/reward ratio – Set a minimum ratio. For example, 1:3 means you are willing to risk $100 for a potential profit of $300.
1 percent (or 2 percent) rule – Limit your risk to investing no more than 1 percent of your portfolio on any one trade.
By spreading your investments across a variety of assets, you can reduce portfolio losses through diversification.
Remember that investing is replete with uncertainty; not even the most experienced money managers can predict the direction of the markets. Developing an exit strategy for stock holdings is a way to minimize potential losses while strategically targeting specific returns to meet your goals.
Do You Have an Investment Exit Strategy?
November 1, 2022 · Blog, Financial Planning
⏱ 4 min read
Are you a trader or an investor? The difference is frequently discerned by how closely you monitor the stock market and how quickly you move in and out of investments. Traders are often referred to as market timers because they actively seek to buy into positions when share prices drop, and sell out when those prices rise.
Many financial planners and professional money managers are not strong proponents of market timing. The reality is that no one can predict market movements accurately over the long term, so success is often a matter of luck and opportunity.
However, market timing is not the same as having a carefully structured and disciplined investment exit strategy. One reason this is important is that it can help prevent investors from panic selling. If you have considered the growth potential and market risks of a particular security or type of investment, and you put parameters in place that reflect your comfort level, then you can control your losses to a great extent. Without this analysis, you may be subject to emotional responses and sell for a significant loss because you can’t take the stress of watching your investment lose money day after day.
Exit Strategy
When share prices drop unexpectedly – and continue to fall – many investors let their emotions get the best of them and sell prematurely. Having a preconceived exit strategy is a good way to prevent this type of panic selling.
An exit strategy basically means that you set a target sell price, but it’s important that you have the discipline to sell at that price. Often when a stock’s share price is rising quickly, it is tempting to “let it ride” and ignore your exit strategy. However, that tide could change quickly in the other direction, turning a profitable trade into a loss. When this happens, you may stubbornly hang on to that declining stock knowing that you missed your opportunity to cash in – and hope that it will come around again.
An effective exit strategy should have two plans in place; a price point to sell for a gain and a price point to sell for a loss. This tactic can help keep your asset allocation strategy on target by not letting gains or losses in any one position throw your target asset allocation percentages out of whack. At the same time, you can manage risk by not allowing your portfolio to lose too much money. There are certain tactics that can help implement your exit strategy. For example:
Stop-Loss – an order to sell a security when its price is declining at the point when it reaches your assigned stop price (sell-stop).
Stop-Limit – a limit order gives instructions to sell a stock at a minimum price point. Stop-limit orders can be set to expire at the end of the current market session or carried over to future trading sessions (GTC – good ‘til canceled).
Trailing Stop – a modified stop order that can be set as either a percentage or dollar amount below or above the market price of a security.
Tax Considerations
An investor’s exit strategy should take into consideration potential taxes on capital gains. The amount you pay depends on how long you hold a position. If held for less than one year, the short-term capital gains tax rate is the same as your regular income tax. If held for one year or longer, the tax rate is 0 percent, 15 percent or 20 percent – depending on income tax bracket and filing status. When determining your exit strategy, it is prudent to set a long-term perspective with a plan to harvest gains on positions more than a year old.
Risk Management
Setting up an exit strategy is one component of a risk management plan. The following are other complementary strategies you can deploy to set boundaries on how much money you are willing lose.
Risk/reward ratio – Set a minimum ratio. For example, 1:3 means you are willing to risk $100 for a potential profit of $300.
1 percent (or 2 percent) rule – Limit your risk to investing no more than 1 percent of your portfolio on any one trade.
By spreading your investments across a variety of assets, you can reduce portfolio losses through diversification.
Remember that investing is replete with uncertainty; not even the most experienced money managers can predict the direction of the markets. Developing an exit strategy for stock holdings is a way to minimize potential losses while strategically targeting specific returns to meet your goals.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Early technology adopters are more likely to gain better business results, including higher revenue growth and market position. With businesses facing complex problems every day, it is no doubt that they are always watching out for the next big tech that offers a better solution.
Although still in its infancy stages, quantum computing is a technology whose commercial use will disrupt the business environment.
What is Quantum Computing?
Quantum computing is a technology that focuses on manipulating and controlling different laws of physics. This non-classical technology uses quantum mechanical concepts like superposition and quantum entanglement.
The idea of quantum computing is not new and has come a long way. The first algorithm of large integer factorization for quantum computing was introduced in 1994. This algorithm intended to reduce the time it would take classical computers to find the prime factors of large numbers. It’s worth noting that the majority of the current infrastructure for encryption and information security is built on prime factorization.
Since the first algorithm was developed, more technological advances have been reported, and the field is continuously receiving funding. According to the McKinsey & Company Quantum Technology Monitor, funding from private and public sectors for this new technology is skyrocketing worldwide.
How it Works
Unlike classical computing, whose information is encoded by bits, in quantum computing a qubit is the basic unit of quantum information. Qubit allows all combinations of information to exist simultaneously so that quantum computers can solve problems exponentially faster and with less energy consumption than classical computers.
Advanced development in this technology has also seen the introduction of quantum-computing cloud infrastructure through Quantum as a Service (QaaS). QaaS provides access to quantum computing platforms over the internet to customers. Major technology companies, such as Amazon, Alibaba, IBM, Google, and Microsoft, have already launched commercial cloud services for quantum computing.
With the continued increase in the quantum computing ecosystem and emerging business use cases, business leaders must stay aware and prepare to adopt the new technology.
Business Use Cases for Quantum Computing
1. Quick Data Analytics
Today more than ever, businesses are faced with big data and a large quantity of information requiring analysis and storage. Since classical computers are built to solve one task at a time, it takes longer to solve these complex problems.
However, quantum technology has the potential to turn complex computations into simple calculations that are solved in less time.
2. Optimize Investment Strategies
Optimization is all about finding the most ideal solution in a situation. When many options are available, it takes a classical computer a long time to find a solution. Therefore, classical computers use shortcuts, and the final solution is partly optimal. But, with quantum computing, there will be better optimization.
3. Better Forecast and Prediction
Businesses rely on forecasts and predictions generated after analyzing complex and large data sets. Quantum computing is built to process huge amounts of data quickly and more accurately. As a result, better forecasts and predictions will enable better decision-making.
4. Solve Problems With Financial Services
There are various computationally intensive jobs in finance that could be facilitated by quantum computing, such as credit-risk management, financial crime reduction, and trading strategy optimization. These tasks will greatly benefit from quantum algorithms that increase the speed of financial calculations.
5. Improve Data Security
Quantum computers are built to break encryptions that ordinary computers cannot. This might become a problem if hackers were to acquire encrypted data and store it until large-scale quantum computers are operational. To handle this problem, postquantum cryptography, a type of cyber security that can be used by conventional computers, is currently being developed. Therefore, a switch to quantum-resistant cryptography will prevent the possibility of data being exposed. At the same time, it will ensure better protection of digital assets.
Final Thoughts
Quantum computers will not replace classical computers; however, the two will form a hybrid solution whereby each task will be assigned to the most suitable machine – either quantum or classical.
Achieving the aforementioned benefits will require businesses to have teams of experts who are knowledgeable about the implications of quantum computing and who can recognize the company’s potential future needs, opportunities, and vulnerabilities.
With signs of commercial quantum computing becoming a reality, it’s not too early for business leaders to consider how it will encourage digital investment, reshape industries and ignite innovation. Therefore, having a thorough understanding of quantum applications is essential for positioning a business to gain a competitive edge.
Quantum Computing Uses That Solve Business Problems
November 1, 2022 · Blog, What's New in Technology
⏱ 4 min read
Early technology adopters are more likely to gain better business results, including higher revenue growth and market position. With businesses facing complex problems every day, it is no doubt that they are always watching out for the next big tech that offers a better solution.
Although still in its infancy stages, quantum computing is a technology whose commercial use will disrupt the business environment.
What is Quantum Computing?
Quantum computing is a technology that focuses on manipulating and controlling different laws of physics. This non-classical technology uses quantum mechanical concepts like superposition and quantum entanglement.
The idea of quantum computing is not new and has come a long way. The first algorithm of large integer factorization for quantum computing was introduced in 1994. This algorithm intended to reduce the time it would take classical computers to find the prime factors of large numbers. It’s worth noting that the majority of the current infrastructure for encryption and information security is built on prime factorization.
Since the first algorithm was developed, more technological advances have been reported, and the field is continuously receiving funding. According to the McKinsey & Company Quantum Technology Monitor, funding from private and public sectors for this new technology is skyrocketing worldwide.
How it Works
Unlike classical computing, whose information is encoded by bits, in quantum computing a qubit is the basic unit of quantum information. Qubit allows all combinations of information to exist simultaneously so that quantum computers can solve problems exponentially faster and with less energy consumption than classical computers.
Advanced development in this technology has also seen the introduction of quantum-computing cloud infrastructure through Quantum as a Service (QaaS). QaaS provides access to quantum computing platforms over the internet to customers. Major technology companies, such as Amazon, Alibaba, IBM, Google, and Microsoft, have already launched commercial cloud services for quantum computing.
With the continued increase in the quantum computing ecosystem and emerging business use cases, business leaders must stay aware and prepare to adopt the new technology.
Business Use Cases for Quantum Computing
1. Quick Data Analytics
Today more than ever, businesses are faced with big data and a large quantity of information requiring analysis and storage. Since classical computers are built to solve one task at a time, it takes longer to solve these complex problems.
However, quantum technology has the potential to turn complex computations into simple calculations that are solved in less time.
2. Optimize Investment Strategies
Optimization is all about finding the most ideal solution in a situation. When many options are available, it takes a classical computer a long time to find a solution. Therefore, classical computers use shortcuts, and the final solution is partly optimal. But, with quantum computing, there will be better optimization.
3. Better Forecast and Prediction
Businesses rely on forecasts and predictions generated after analyzing complex and large data sets. Quantum computing is built to process huge amounts of data quickly and more accurately. As a result, better forecasts and predictions will enable better decision-making.
4. Solve Problems With Financial Services
There are various computationally intensive jobs in finance that could be facilitated by quantum computing, such as credit-risk management, financial crime reduction, and trading strategy optimization. These tasks will greatly benefit from quantum algorithms that increase the speed of financial calculations.
5. Improve Data Security
Quantum computers are built to break encryptions that ordinary computers cannot. This might become a problem if hackers were to acquire encrypted data and store it until large-scale quantum computers are operational. To handle this problem, postquantum cryptography, a type of cyber security that can be used by conventional computers, is currently being developed. Therefore, a switch to quantum-resistant cryptography will prevent the possibility of data being exposed. At the same time, it will ensure better protection of digital assets.
Final Thoughts
Quantum computers will not replace classical computers; however, the two will form a hybrid solution whereby each task will be assigned to the most suitable machine – either quantum or classical.
Achieving the aforementioned benefits will require businesses to have teams of experts who are knowledgeable about the implications of quantum computing and who can recognize the company’s potential future needs, opportunities, and vulnerabilities.
With signs of commercial quantum computing becoming a reality, it’s not too early for business leaders to consider how it will encourage digital investment, reshape industries and ignite innovation. Therefore, having a thorough understanding of quantum applications is essential for positioning a business to gain a competitive edge.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Auditing typically refers to an objective review of a company’s financial statements, which consists of the cash flow statement, the income statement and the balance sheet. It analyzes the level of accuracy that the business has characterized its financial records. The process looks at how a business documents investing, financing and operating ventures.
Depending on the type of audit and what it aims to accomplish, it can be conducted by internal employees or independent, third-party examiners like a Certified Public Accountant (CPA) firm or a government agency such as the Internal Revenue Service. When it comes to the United States, the Generally Accepted Accounting Principles (GAAP) is what auditors look to when analyzing financial statement preparation. External audits are guided by the American Institute of Certified Public Accountants’ (AICPA) Auditing Standards Board (ASB). The AICPA requires that the generally accepted auditing standards (GAAS) are followed by external auditors to ensure proper protocol is followed.
When it comes to regulations, the Sarbanes-Oxley Act of 2002 requires publicly traded companies to have their internal controls’ impacts reviewed. It also states that companies that do not implement and enforce their internal controls may be subject to criminal charges.
Defining Internal Controls
These can be thought of as how businesses can manage operations by regulating permissions, documentation, congruency, protection/safety and partitioning of responsibilities for business processes. These are broken into preventative and detective activities.
Sometimes referred to as protective activities, responsibilities are compartmentalized and distributed among different individuals to dissuade mistakes or deceit from occurring.
It also integrates highly detailed written procedures and validation procedures for further cautionary measures. It’s meant to verify that no sole person is able to approve, document or be responsible for monetary transactions and final products. Permitting invoices and validation of expenses are examples of internal controls. Only permitting appropriate access to the fewest employees necessary and the fewest required business equipment is one way to implement this type of internal control.
Detective Controls Defined
These are redundant systems that are put in place to intercept issues that might have fallen through the initial round of quality control measures. Looking to reconciliation procedures, which matches data in question against known accurate data sets, it’s used to fix discrepancies.
Internal Audits
This type of audit is usually conducted by the business’ employees, primarily performed as a way to evaluate internal operations and internal controls. It looks to identify any deficiencies or weaknesses in the business’ operations, often occurring before an external auditor reviews its financial statements. It’s also meant to review and identify any legal or regulatory compliance issues.
External Audits
This type of audit occurs when an independent auditor, such as a third-party CPA firm, assesses a business’ internal controls and financial statements. It is performed to provide an objective opinion that an audit conducted by the business itself cannot. With a “clean opinion” or “unqualified opinion” provided by the independent auditor, businesses can provide those looking at financial statements confidence that such financial statements are reliable. It enables the outside entity to focus on the financials, the business’ internal controls, etc. by providing a conflict-of-interest-free perspective.
Government Audits
This type of audit is done to ensure that businesses have accurately reported their taxable income to respective government agencies. This can include federal agencies such as the Internal Revenue Service (IRS) and Canada Revenue Agency (CRA), which are the U.S. and Canada’s respective tax collection agencies.
When an IRS audit has concluded its review, there may be a few different preliminary results and resulting paths. The tax return may see no modification. There may be a modification the taxpayer agrees to, which could result in additional money being owed. The third result occurs when the filer doesn’t agree with the change, and it is worked out through an appeal process.
Whether it’s an investor for a publicly traded company or a business looking for creditors for help with money, materials, etc., having audited financial statements provides confidence that they’ll see a return on their investment or a high likelihood of their debts being satisfied in the future.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 When there’s a question of the benefit that tangible or intangible assets provide businesses, there are many factors that must be weighed to make internal accounting procedures effective. Businesses must determine how the cost of business assets can be expensed each year over the asset’s lifespan. Looking at how amortization and depreciation work, implementing both processes depend on the type of asset being expensed. There are noticeable differences for each method, including how to salvage value is considered, whether accelerated expensing is allowed, and how each type is expressed on financial statements.



 By 2021, there were 20,000 warehouses in the United States and growing, according to the United States Bureau of Labor Statistics (BLS). With more warehouses expected to pop up in 2022 and beyond, one important consideration for businesses of all sizes is to keep track of their inventories. With different tracking and valuation methods, it’s important to understand how they work and what they can tell business owners.
 Now is the time of year to do everything you can to minimize taxes and maximize your financial health with proper year-end planning. In this article, we’ll look at several actions to consider taking before the end of 2022.
 Data has become a primary asset for businesses today. Consequently, the survival of a business in our data-driven environment is highly dependent on the ability to have total control over data storage, extraction, and manipulation.
 Believe it or not, the year is coming to a close. If you want to finish strong and set attainable goals for 2023, here’s a handy, actionable checklist to help you navigate upcoming expenditures.
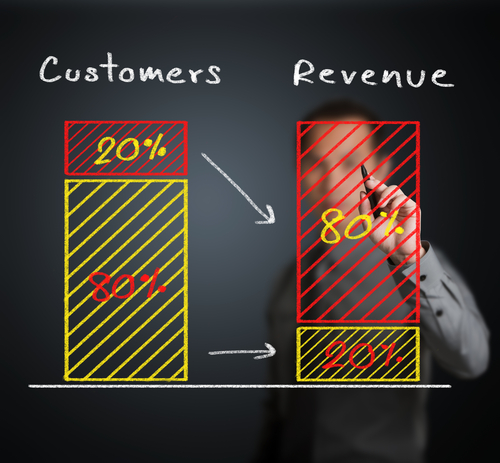 Some businesses, especially publicly traded ones, may choose accrual accounting to reduce volatility in earnings, while start-ups or small businesses may choose to go with a cash basis accounting option. A poll conducted by the Journal of Accountancy on Topic 606 discovered that one in five respondents reported that one of the most common audit perils for their clients was the risk of evaluating “material misstatement” when it comes to recognizing revenue under Topic 606.
 Planning for Animal Wellness Act /PAW Act (S 4205) – Introduced by Sen. Gary Peters (D-MI) on May 12, this act instructs the Federal Emergency Management Agency (FEMA) to compile best practices and federal guidance for handling household pets, service and assistance animals and captive animals during emergencies and disasters. Initiatives include preparedness (e.g., sheltering and evacuation planning), response and recovery.The bill passed in the Senate on Aug. 6, in the House on Sept. 14 and was signed into law on Oct. 17 by President Biden.
 Are you a trader or an investor? The difference is frequently discerned by how closely you monitor the stock market and how quickly you move in and out of investments. Traders are often referred to as market timers because they actively seek to buy into positions when share prices drop, and sell out when those prices rise.
 Early technology adopters are more likely to gain better business results, including higher revenue growth and market position. With businesses facing complex problems every day, it is no doubt that they are always watching out for the next big tech that offers a better solution.
 The Importance of Auditing